Investors who are tired of fielding late-night maintenance calls or managing tenant turnover often look for a way to stay invested in real estate without the day-to-day headaches of active management. A 1031 exchange NNN lease properties strategy is one of the most common answers to that problem: sell an actively managed asset, such as an apartment building or a mixed-use property, and exchange into a single-tenant net lease building where the tenant handles most of the property-level responsibilities. This guide covers what a NNN lease actually is, why these properties are popular 1031 replacements, and the diligence questions an investor should work through before buying one.
If passive, management-light income is the goal for your next property, talk with Aspen Exchange early in your search so your exchange timeline lines up with the right NNN opportunity.
What Is a Triple Net (NNN) Lease?
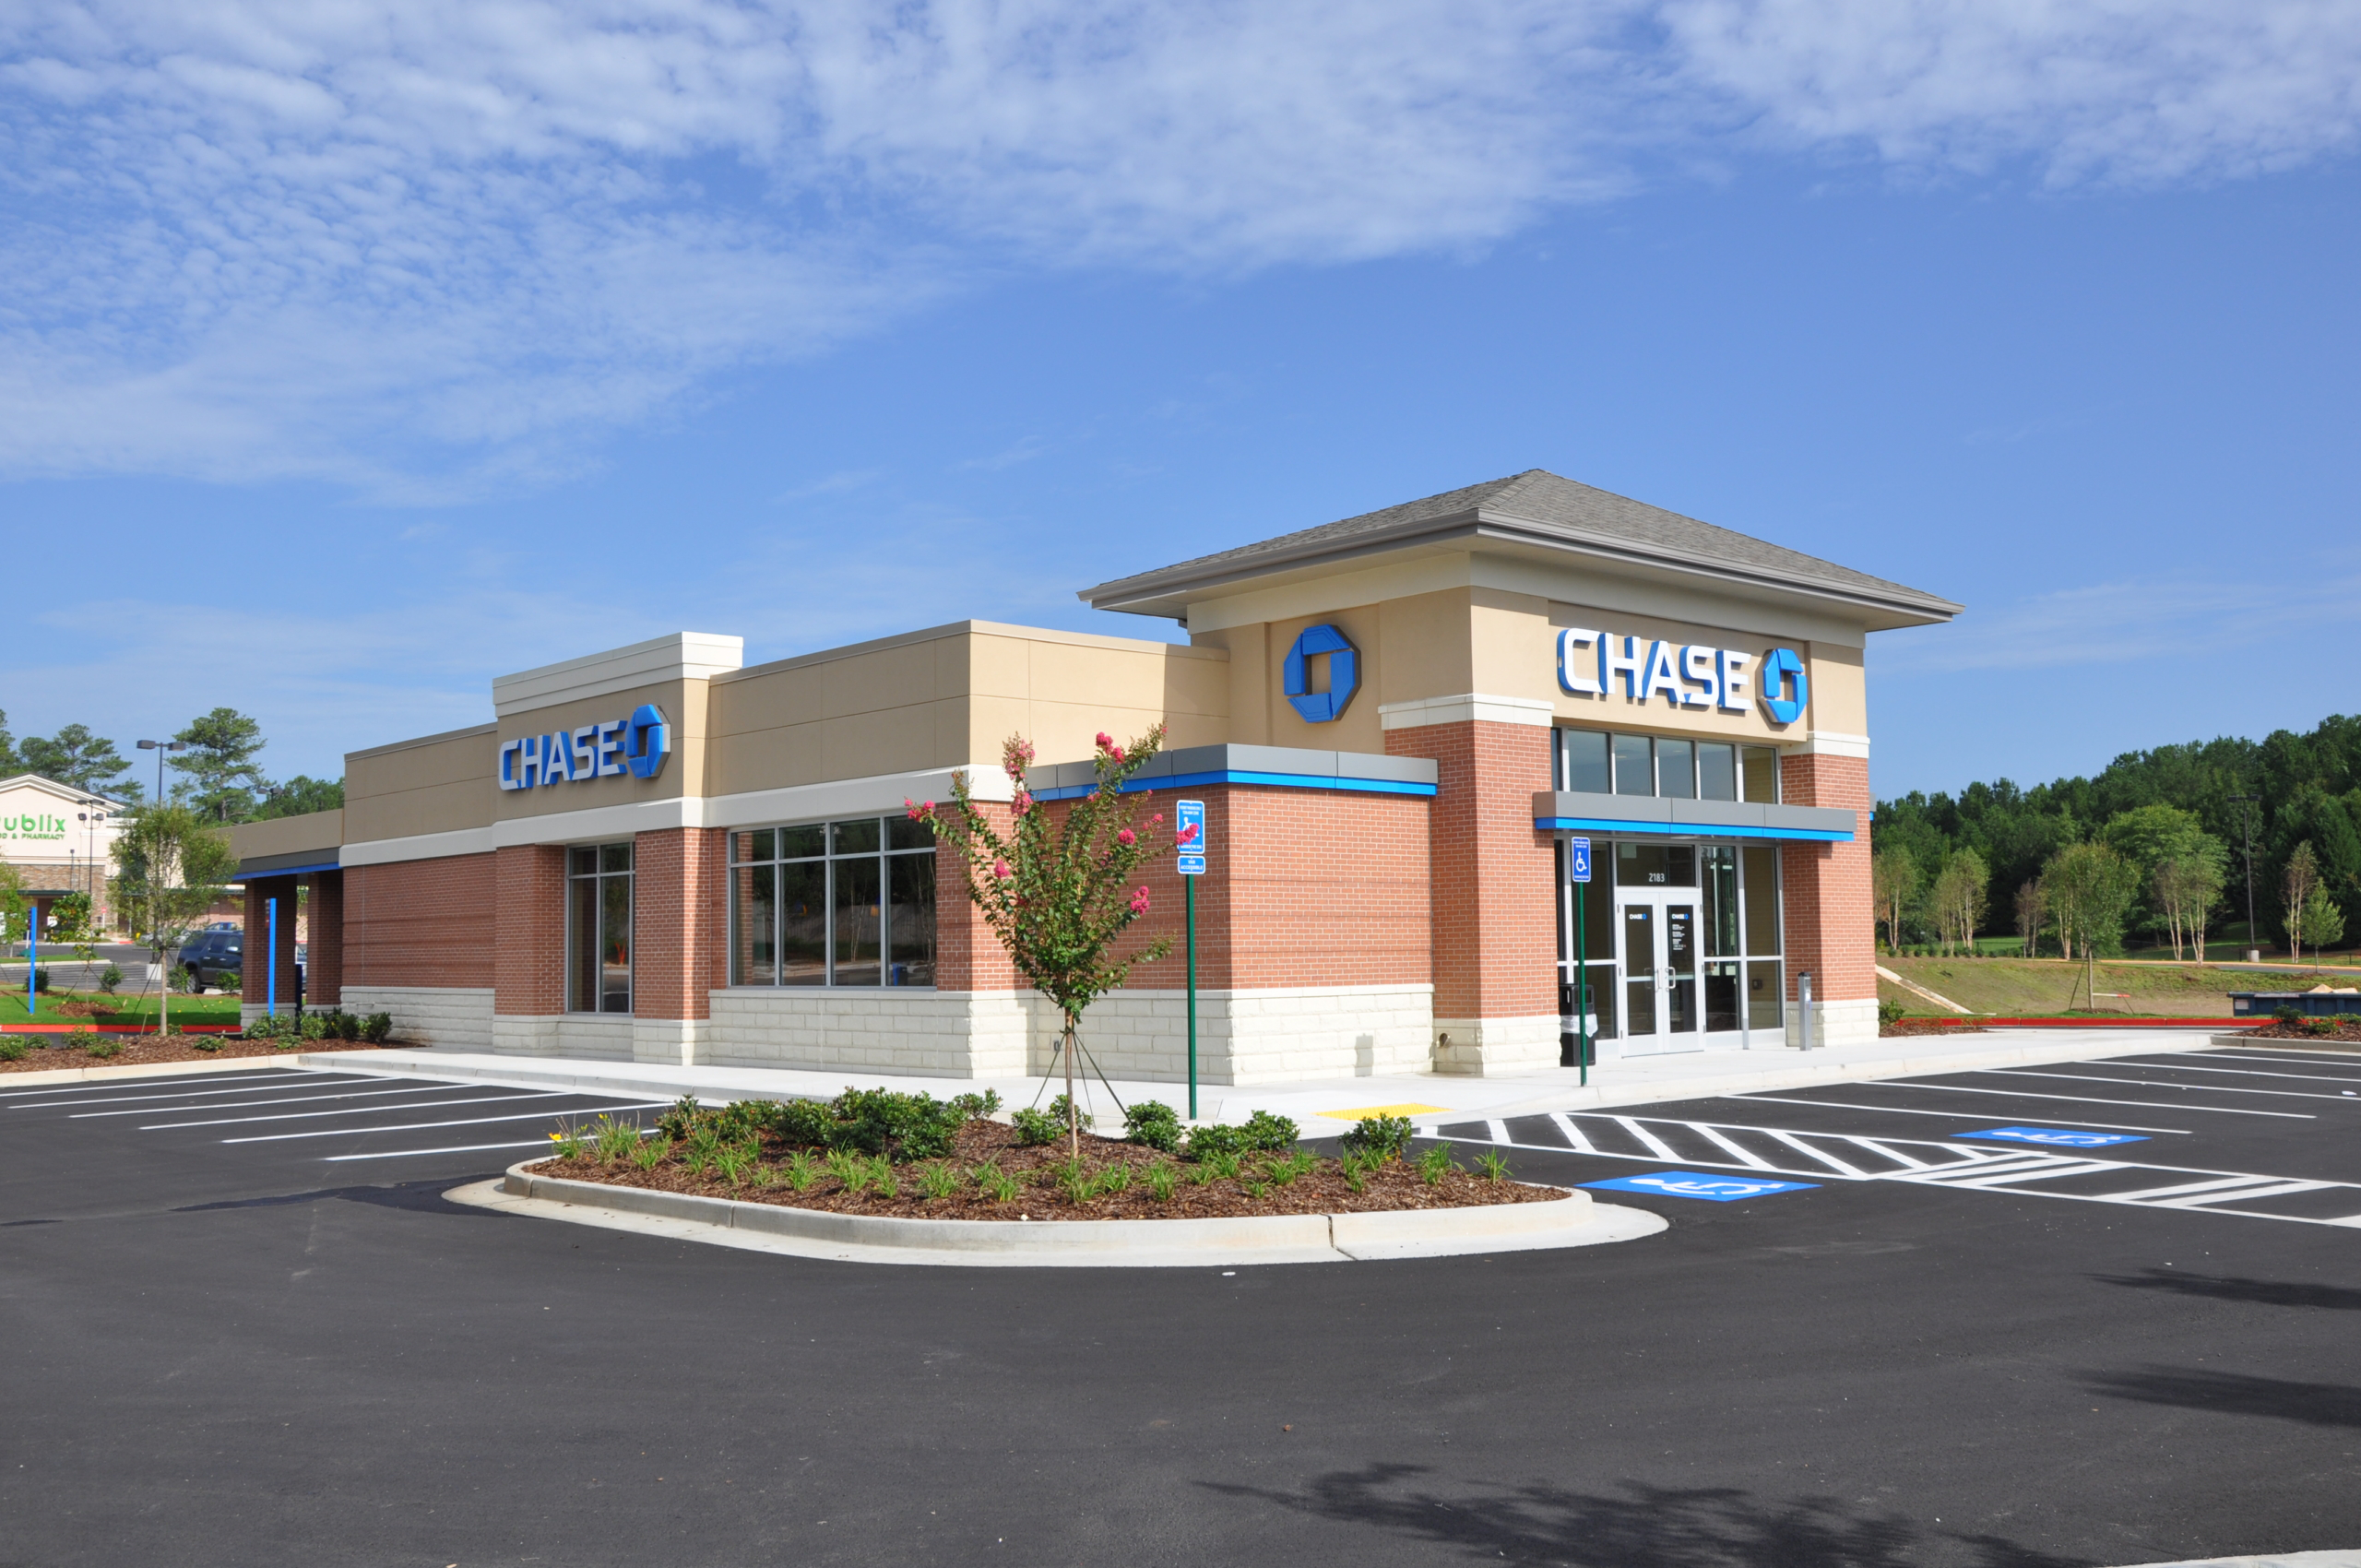
In a triple net lease, the tenant is generally responsible for the three major property expenses beyond rent: property taxes, building insurance, and maintenance costs (the “three nets”). The landlord collects rent and typically has little to no responsibility for day-to-day operating expenses, in contrast to a gross lease, where the landlord covers most of those costs out of the rent collected. NNN leases are most common in single-tenant retail, such as freestanding drugstores, quick-service restaurants, dollar stores, auto parts retailers, and convenience stores, though the structure also shows up in industrial and some office properties.
Why NNN Assets Are Popular 1031 Replacement Properties
Several features make net lease properties a natural fit for exchange buyers looking to reduce management burden:
- Passive ownership. With the tenant responsible for most operating expenses and maintenance, the landlord’s role is largely limited to collecting rent and monitoring lease compliance.
- Predictable, long-term income. Many NNN leases run 10, 15, or even 20 years at signing, often with built-in rent escalations, which appeals to investors who want dependable cash flow.
- Simple closings. Single-tenant net lease properties are widely traded, with standardized lease structures that make underwriting and closing relatively efficient, which matters when working against a 45-day identification deadline.
- A natural fit for the identification rules. Because these deals are common and often priced similarly to the relinquished property, investors can more easily satisfy the exchange’s identification requirements described in this 45-day rule guide.
- Debt replacement flexibility. Net lease properties are often financed with conventional commercial mortgages, which can help an investor match or exceed the debt on the relinquished property, a requirement discussed in this 1031 exchange rules overview.
Tenant Credit Quality Considerations
A net lease is only as reliable as the tenant paying it. Before buying a NNN property as part of an exchange, investors typically look closely at:
- Credit rating. Publicly traded tenants often carry a credit rating from a major agency, which gives some indication of the tenant’s ability to continue paying rent through an economic downturn.
- Corporate guarantee versus franchisee lease. A lease guaranteed by a large corporate parent is generally viewed differently than one signed by an individual franchisee operator, since the franchisee’s financial strength can vary significantly.
- Store performance and unit-level sales. Where available, sales figures for the specific location help gauge whether the store is likely to remain profitable and open through the lease term.
- Industry exposure. Certain retail categories face more structural pressure from e-commerce or changing consumer habits than others, which is worth weighing against the length of the remaining lease term.
Lease Term and Rollover Risk
The remaining term on the lease, and what happens when it ends, is one of the most important variables in evaluating a NNN property. Key questions include:
- How many years remain on the primary lease term, and how many renewal options does the tenant hold.
- Are the renewal options at the tenant’s discretion, and at what rent.
- What happens to the property’s value and marketability if the tenant does not renew and the space needs to be re-leased or repositioned.
- Is the location a strong, replaceable real estate site on its own, independent of the current tenant, in case the lease is not renewed.
A property with a short remaining lease term and no strong underlying real estate fundamentals carries meaningfully more rollover risk than one with a long lease term in a location that would attract other tenants if needed.
Cap Rate Versus Bond-Like Yield Framing
Net lease properties are frequently priced and discussed using capitalization rate, or cap rate, which is the property’s annual net operating income divided by its purchase price. Because a long-term NNN lease to a strong tenant behaves somewhat like a bond, with a fixed, predictable income stream, many investors compare NNN cap rates to bond yields and other fixed-income benchmarks when deciding whether a given price makes sense. Generally speaking, a lower cap rate reflects a market perception of lower risk, often tied to stronger tenant credit, a longer remaining lease term, and a more desirable location, while a higher cap rate typically compensates the buyer for greater risk in one or more of those areas. It is worth remembering that, unlike an actual bond, the investor still owns real estate, which carries its own risks around location, releasing, and property condition that a bond does not.
Diligence Checklist for a NNN Exchange Purchase
- Review the full lease document, not just the summary, including renewal options, rent escalations, and any co-tenancy or exclusivity clauses.
- Confirm who is actually obligated to pay taxes, insurance, and maintenance, since not every lease marketed as “triple net” allocates every expense to the tenant.
- Evaluate the tenant’s credit and, where relevant, the guarantor behind the lease.
- Get an independent property condition assessment, since major structural or roof issues can become the landlord’s responsibility depending on the lease terms.
- Confirm zoning and any use restrictions that could affect re-leasing if the current tenant leaves.
- Check for any pending litigation, environmental issues, or title defects through standard title and survey review.
- Verify the deal timeline against your exchange deadlines, working closely with your qualified intermediary so the closing can happen within the 180-day window.
Frequently Asked Questions
What does “triple net” actually mean in a NNN lease?
It generally refers to the tenant being responsible for the three main property-level expenses beyond rent: property taxes, building insurance, and maintenance. Landlord responsibilities vary by lease, so it is important to confirm the exact terms rather than assume based on the label alone.
Why do 1031 exchange investors like NNN properties?
NNN properties generally require less hands-on management than multifamily or mixed-use assets, offer relatively predictable income, and are common enough in the market to help investors meet the 45-day identification deadline with viable options.
How do I evaluate whether a NNN tenant is a safe bet?
Look at the tenant’s credit rating if available, whether the lease is corporate-guaranteed or signed by an individual franchisee, and how the specific location has performed. A strong location that would attract other tenants is valuable even if the current tenant eventually leaves.
What is rollover risk in a NNN property?
Rollover risk refers to the uncertainty around what happens when the current lease term ends, including whether the tenant renews, at what rent, and how difficult or costly it would be to re-lease the space to a new tenant if they do not.
Is a lower cap rate always better in a NNN property?
Not necessarily. A lower cap rate often reflects lower perceived risk, such as strong tenant credit and a long lease term, but it also means a lower initial yield. The right cap rate depends on the investor’s goals, risk tolerance, and how the property fits into their broader portfolio.
Can I use a 1031 exchange to move from a management-intensive property into a NNN property?
Yes, this is one of the more common uses of a 1031 exchange. Investors frequently exchange out of properties requiring active management, such as multifamily housing, and into single-tenant net lease assets specifically to reduce their management responsibilities while continuing to defer capital gains.
Plan Your NNN Exchange Before You Sell
A net lease purchase can be one of the more straightforward ways to complete a 1031 exchange, but the diligence still matters, since the quality of your income stream depends entirely on the tenant and the lease. Contact Aspen Exchange before you sell your current property so your qualified intermediary is engaged and ready to help you move efficiently once you identify a NNN replacement.
This article is educational information, not tax, legal, or investment advice. Consult your own qualified advisors regarding your transaction.